Credit cards
Buy now, pay later, without losing track. When you pay with a credit card, the app sets aside the money for that purchase so it's ready when the statement arrives. This page covers adding a card, choosing how you'll pay it, following its statements and limit, and planning repayments.
Add a credit card
-
Open the Accounts tab and tap New account.
-
For Account type, choose Credit card.
-
Enter the Account name and the Initial balance. If you owe money on the card, enter it as a negative balance.
-
Optionally fill in the card details:
- Limit: the card's credit limit.
- Closing day: the day the statement closes. Turn on Dynamic closing date if your card closes a fixed number of days before the due date ("Closes 21 days before due date").
- Due day: the day payment is due. Turn on Due date only on business days if it moves to the next business day.
-
Choose a Payment strategy (see below) and save.
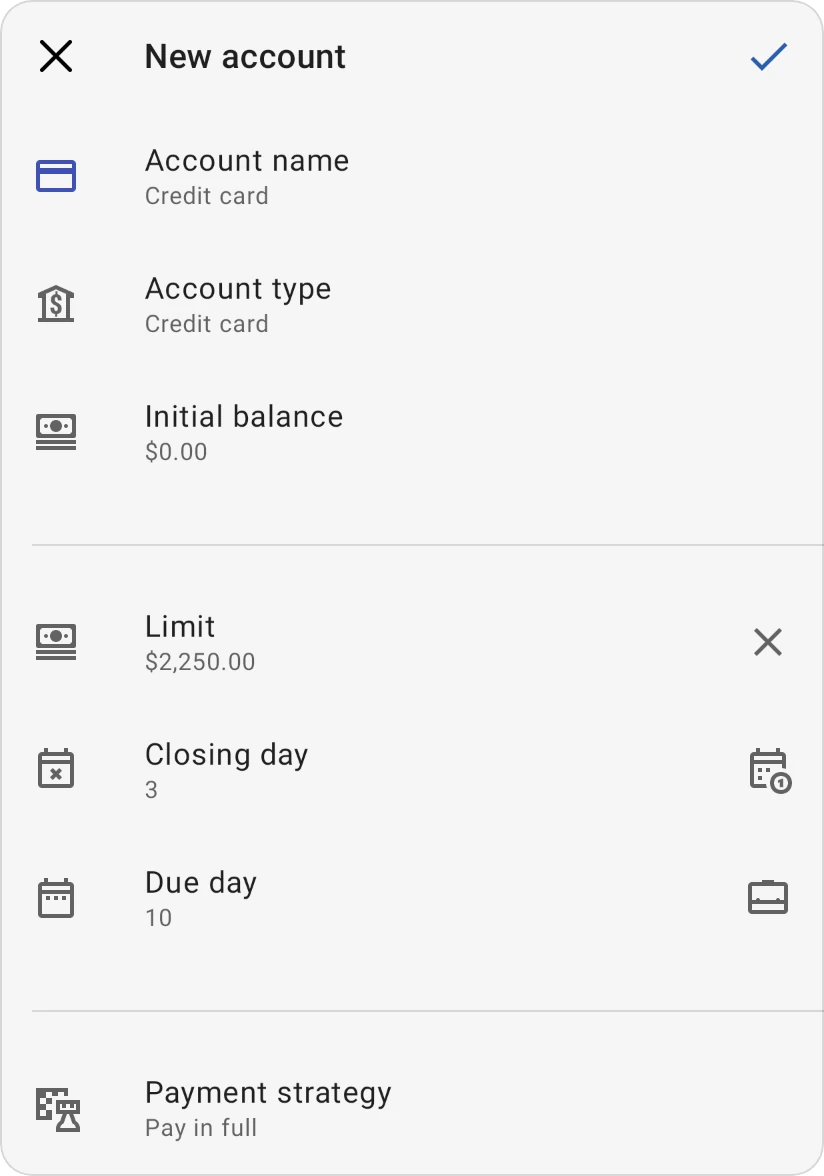
When you create the card, the app adds a category with the card's name to track its expenses, the initial balance and the money set aside for your next statement.
Payment strategies
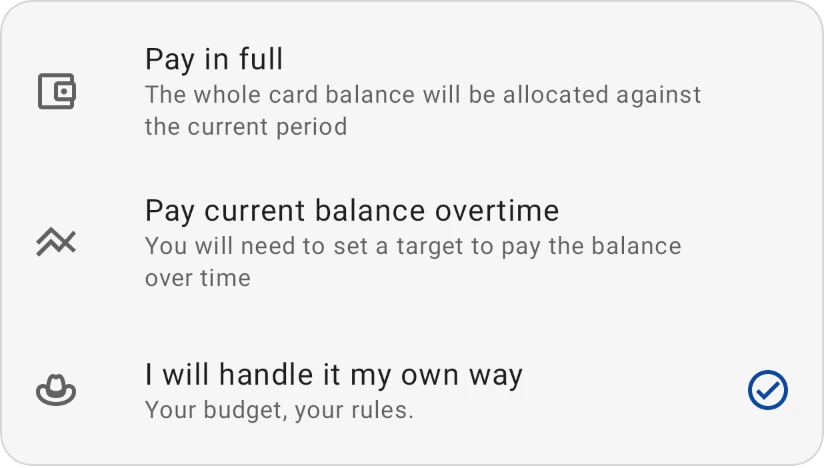
The payment strategy tells the app how you plan to pay the card:
- Pay in full: "The whole card balance will be allocated against the current period." Pick this if you clear the card every month and avoid interest.
- Pay current balance overtime: for a balance you'll pay down over several months. Enter the Annual interest rate, then either a Payoff date or a Monthly payment (the other is calculated), and see how an Extra payment saves you interest. The picker describes it as "You will need to set a target to pay the balance over time", but you don't have to: when you save the card, the app sets a monthly Get out of debt target on the card's category for that Monthly payment (plus any extra payment). These fields are available when the initial balance is negative.
- I will handle it my own way: "Your budget, your rules." The app doesn't plan any payments for you; it still tracks your spending and the balance.
How card spending works
When you record a purchase on the card, for example $50 in Groceries:
- The $50 comes out of Groceries, as with any expense.
- The same $50 moves into the card's category, ready for the payment.
So the card's category always shows how much money you have set aside for the next payment, and you never count the same money twice. For the same reason, credit card payments aren't counted in your monthly spending totals: the purchases were already counted in the categories they came from.
On the Budget tab, the group that holds your cards shows Total to repay instead of Available. Tap the card's category and open its settings to see Credit Card Repayment Details.
Follow your statements
Open the Accounts tab and tap the card to see its details. Along with the limit, closing day and due day, it summarises the card's statement cycle once the card has a Closing day:
- Since last closing date: Spent, Credits and adjustments and your Average daily spending since the last statement closed, the spending that goes on your next statement.
- Billed But Unpaid: what your last statement billed and how much of it is still to pay. See Billed But Unpaid.
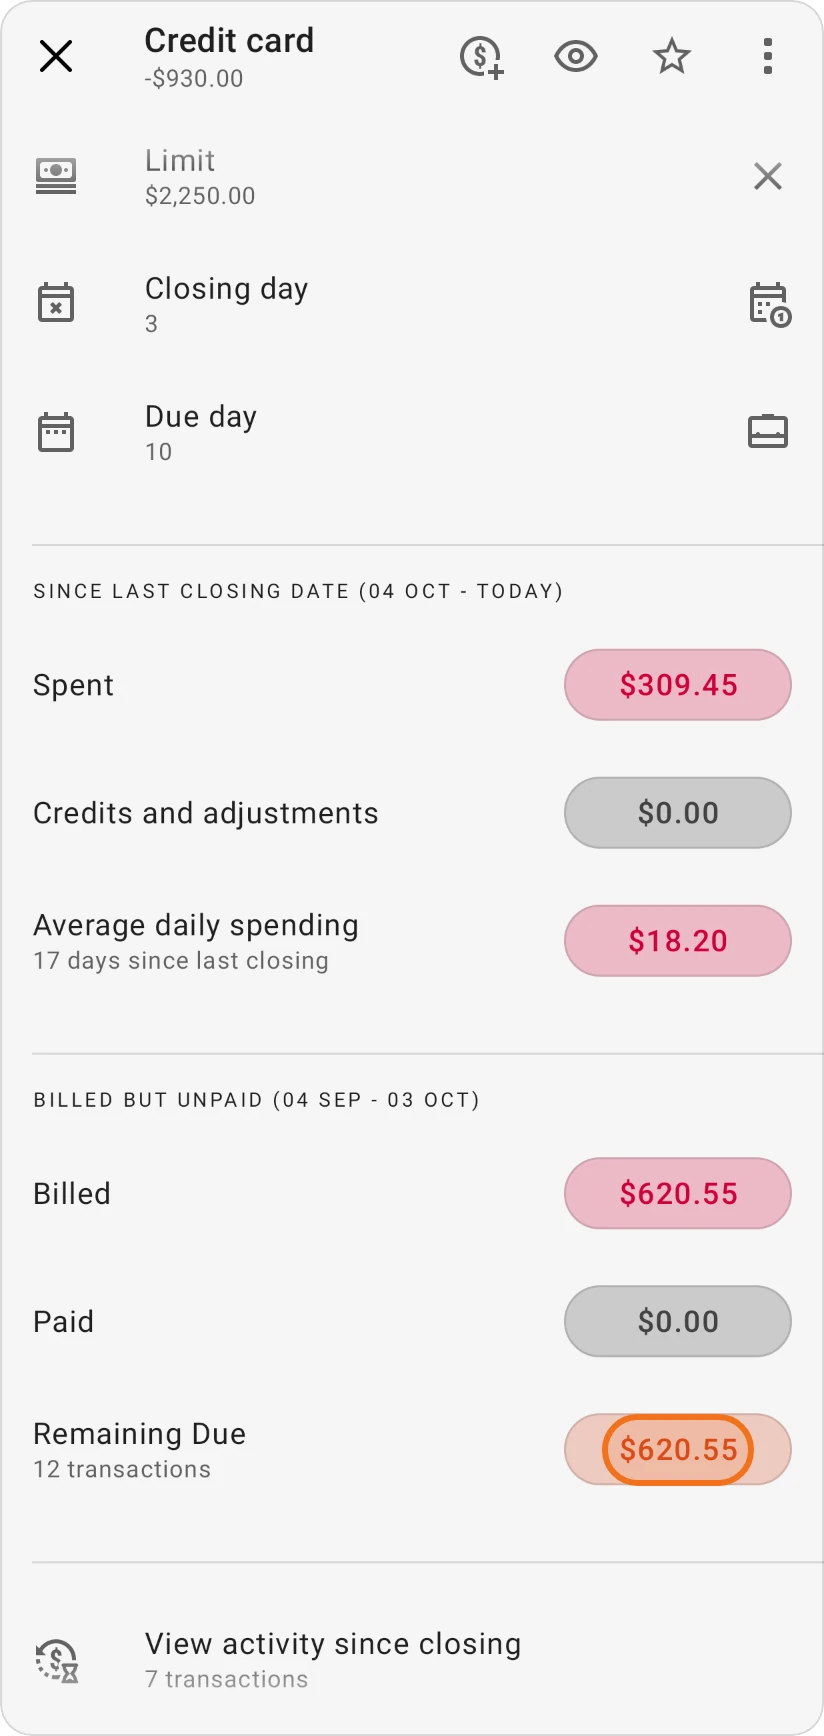
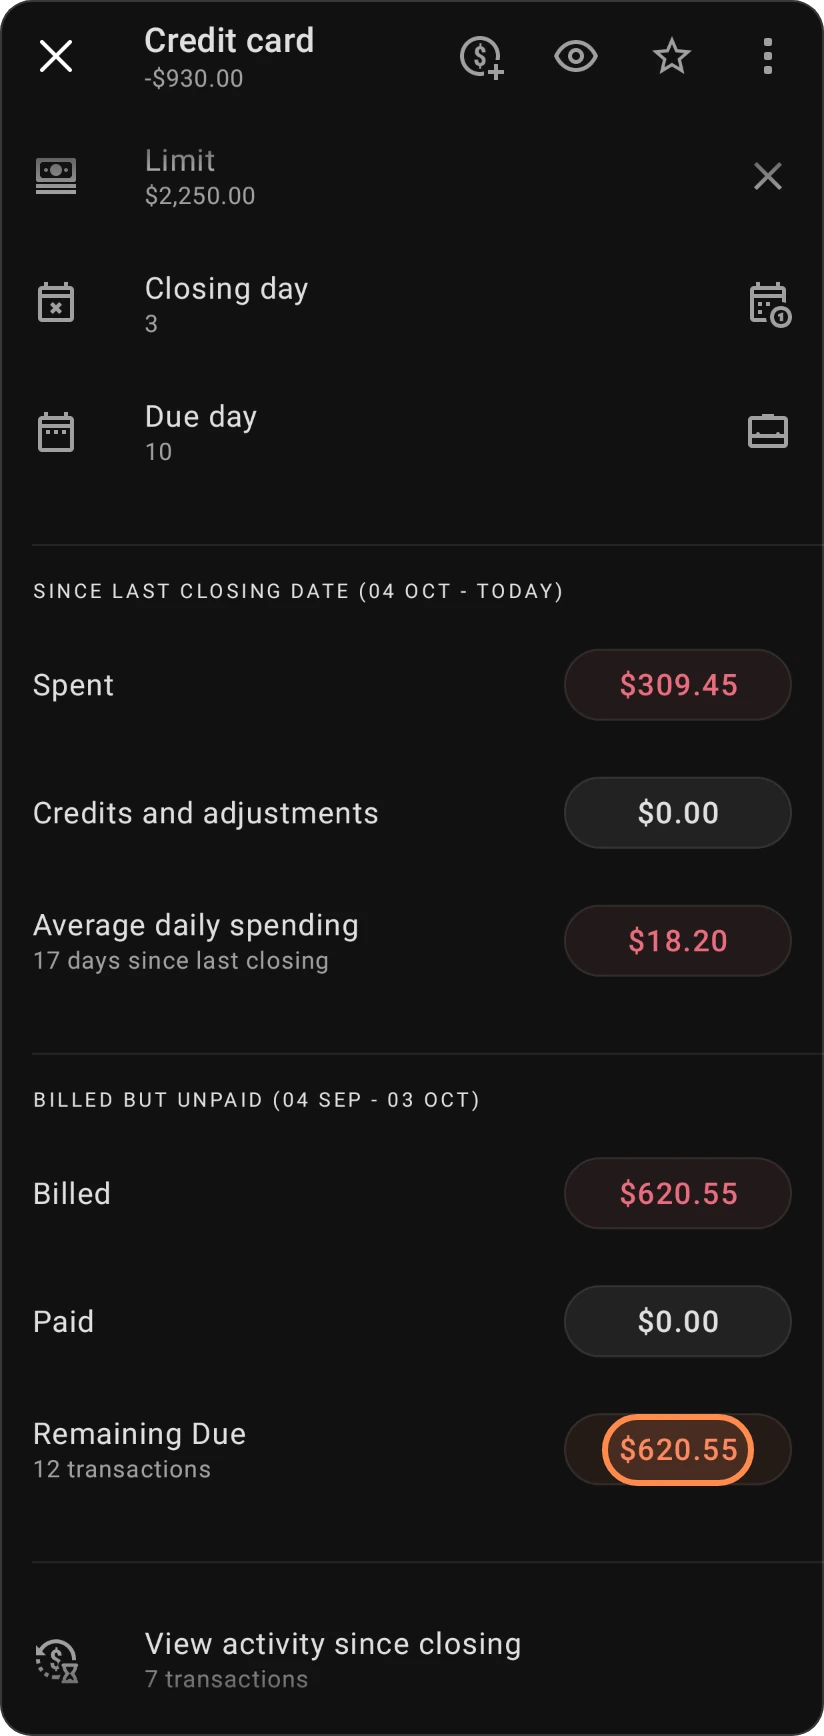
Below them, View activity since closing lists the transactions since the last statement closed, and View billed transactions lists the ones on the last statement.
View activity since closing and View billed transactions are part of the Pro credit card management tools: "Unlock full credit card management tools—track every transaction since your last statement and take charge of your card activity." The summaries themselves show on every plan.
Billed But Unpaid
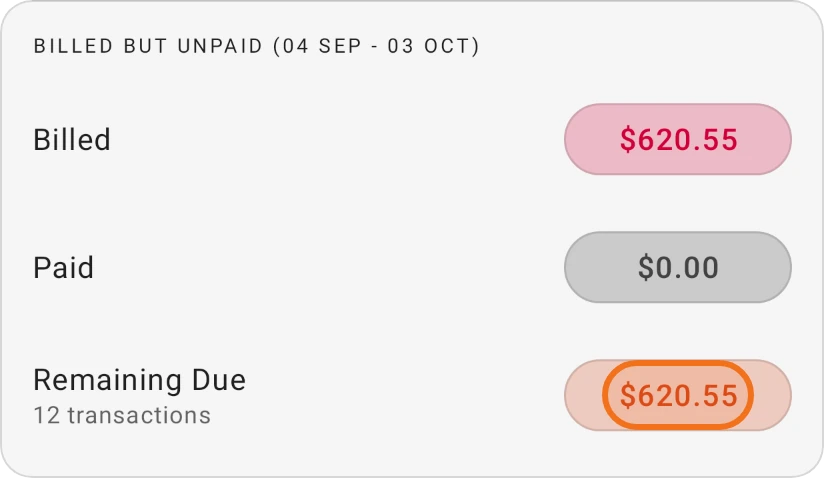
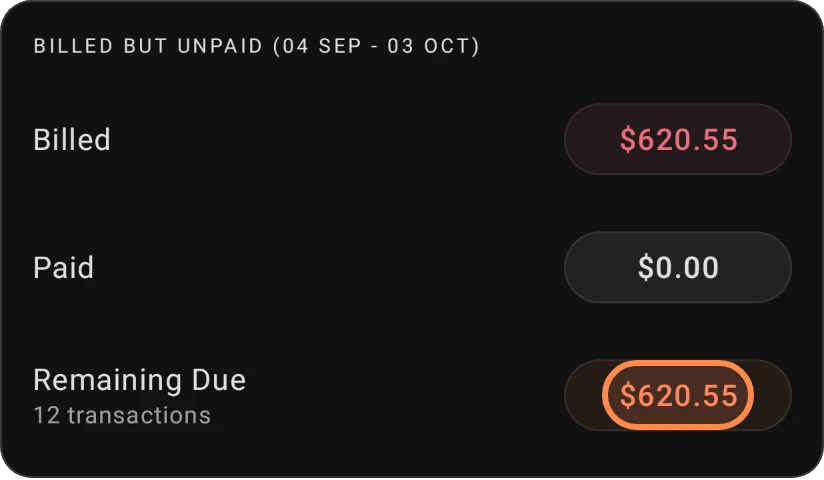
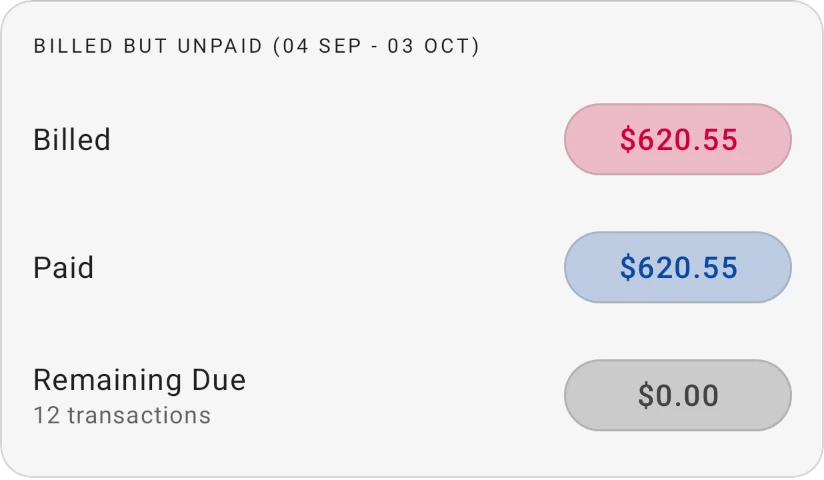
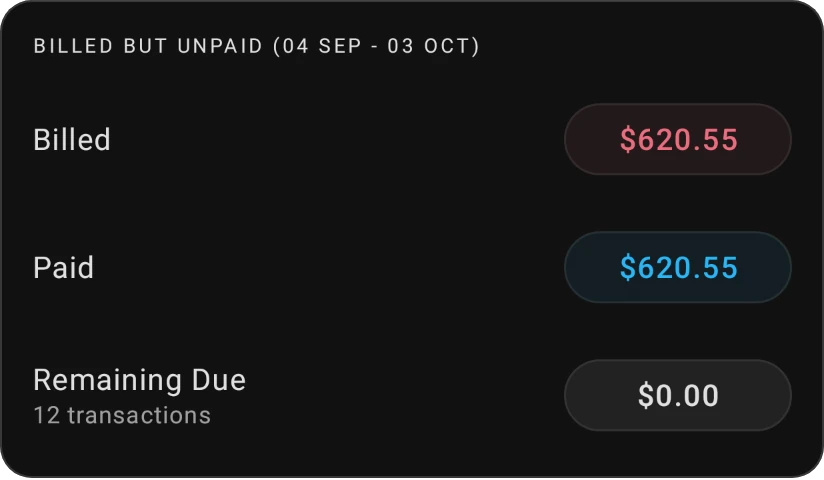
The Billed But Unpaid section covers the last statement: from the day after the closing day a month earlier up to the last closing day. Its title shows those dates, as Billed But Unpaid (start - end). It counts the transactions recorded on the card in that period:
- Billed: what you spent on the card in that period.
- Paid: the payments you've made to the card since the statement closed.
- Remaining Due: what's left to pay on that statement: Billed, less Paid, less that period's credits and refunds. It never goes below zero. The line under it shows how many transactions the statement has.
For example, the statement billed $480 with a $30 refund in the same period. After you pay $200 on 20 October, Paid shows $200 and Remaining Due $250.
Every payment to the card after the closing day counts towards Paid, even one larger than the statement: pay the whole balance and Remaining Due is 0.
One card cycle, step by step
How a month with a credit card goes, in the order you live it. It assumes the card has a Closing day and a Due day (see Add a credit card).
-
Spend on the card. Record each purchase on the card in its usual category. The money moves into the card's category, ready for the payment (see How card spending works). On the card's details, Since last closing date adds it up.
-
The statement closes. On the closing day, that period's spending becomes your statement. Once the closing day has passed, Billed But Unpaid shows it with the period's dates, and Since last closing date starts again for the next statement.
-
Check what's due. Remaining Due under Billed But Unpaid is what you still owe on the statement. View billed transactions lists what's on it.
-
Pay before the due day. Tap Add payment on the card and choose the account the money comes From. Enter the Remaining Due as the Amount to pay the statement, or tap Pay balance to pay everything you owe on the card, new spending included. See Pay off your card.
-
Check it's paid. Back on the card's details, Paid shows your payment and Remaining Due reaches 0. The card's balance and the money set aside in its category go down by the payment.
Then the cycle starts again: your spending since the closing day goes on the next statement.
Interest and fees on your card
The app doesn't add card interest or fees for you. When your statement shows them, record each as an expense on the card, like any purchase: From the card, in a category you keep for them (for example Bank fees). As with any card purchase, the amount comes out of that category and moves into the card's category, so it's set aside for your payment, and the card's balance matches your statement. See Expense.
See how much of your limit is left
When the card has a Limit, its details also show what you can still spend:
- Available now: your limit minus what you owe on the card today. It's the amount your bank shows as available.
- Scheduled charges: the future and recurring transactions you've scheduled on the card, including recurring installments. For a series with a set number of payments, every payment still to come counts. This line shows when something is scheduled.
- Limit left: what's left of your limit once your scheduled charges go through. It shows when something is scheduled; otherwise it would equal Available now. Below zero, your scheduled charges would take you over your limit.
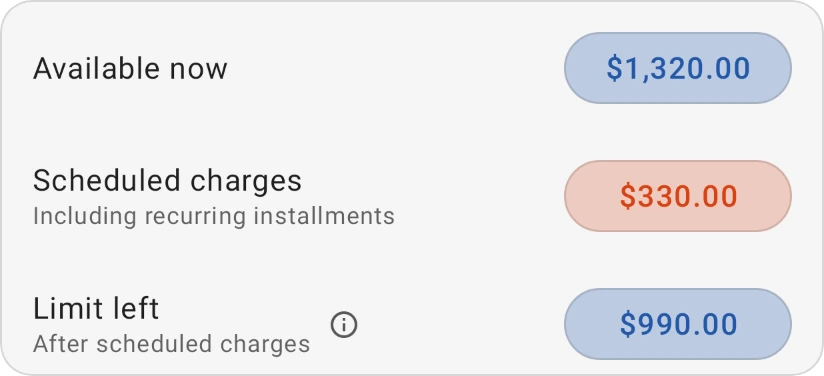
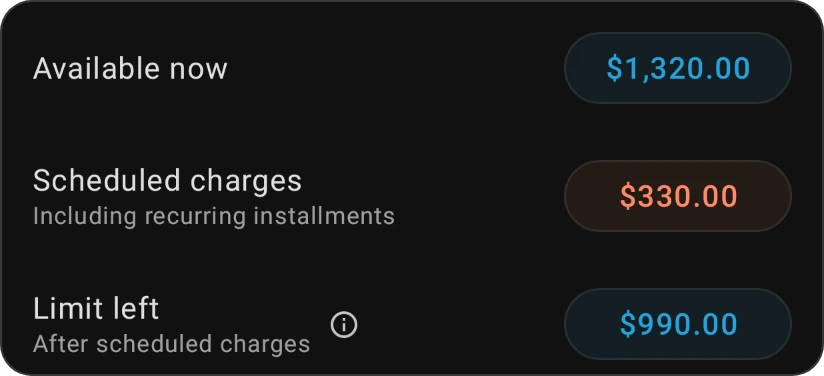
For example, with a $1,000 limit, $600 owed today and three $100 installments still to come, Available now is $400, Scheduled charges are $300 and Limit left is $100.
Tap the info button next to Limit left for a short explanation of both amounts.
Pay off your card
- Open the card from the Accounts tab (or tap the card's category on the Budget tab and open its settings).
- Tap Add payment.
- Choose the account the money comes From and enter the Amount, or tap Pay balance to pay the full balance.
- Check the Date and save.
The payment lowers the card's balance and the money set aside in its category. If you pay more than you owe, the app warns you that the extra will become a credit on your card.
Plan repayments with the credit card calculator
Open the menu (the ☰ button at the top left of the Budget tab) and choose Credit cards to open the Credit card calculator. You'll find the same tool as Debt calculator in a card's ⋮ menu and in a Get out of debt target.
- Under Credit card details, enter the balance Amount and the Annual interest rate.
- Enter a Payoff date or a Monthly payment. The calculator works out the other, plus the Total interest and Total to be paid.
- Under What if I add an extra payment?, add an Extra payment to see how much you'd save, for example "Save $420.00 in interest and reduce the remaining term by 5 months." The chart compares the Original balance with the Balance after extra payments.
- Choose how the extra is paid: Every payment adds it to each monthly payment; One time pays it once, off the balance, Now or in a later month you pick under When. Each choice keeps its own amount. See the loan calculator for how the two work.
When you open the calculator from a target, Set as target uses the result as the target's amount. With a One time extra, only the payment without the extra can be set as the target.
Even small extra payments add up. Paying a little more each month can cut the total interest and get you debt-free sooner.
The calculator is a guide: actual amounts and dates can vary by card issuer because of rounding, fees and other factors.